Your Local Mortgage Lender
Located in Maryland
Personalized Mortgage Experience
Geoff Ricker offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Maryland.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
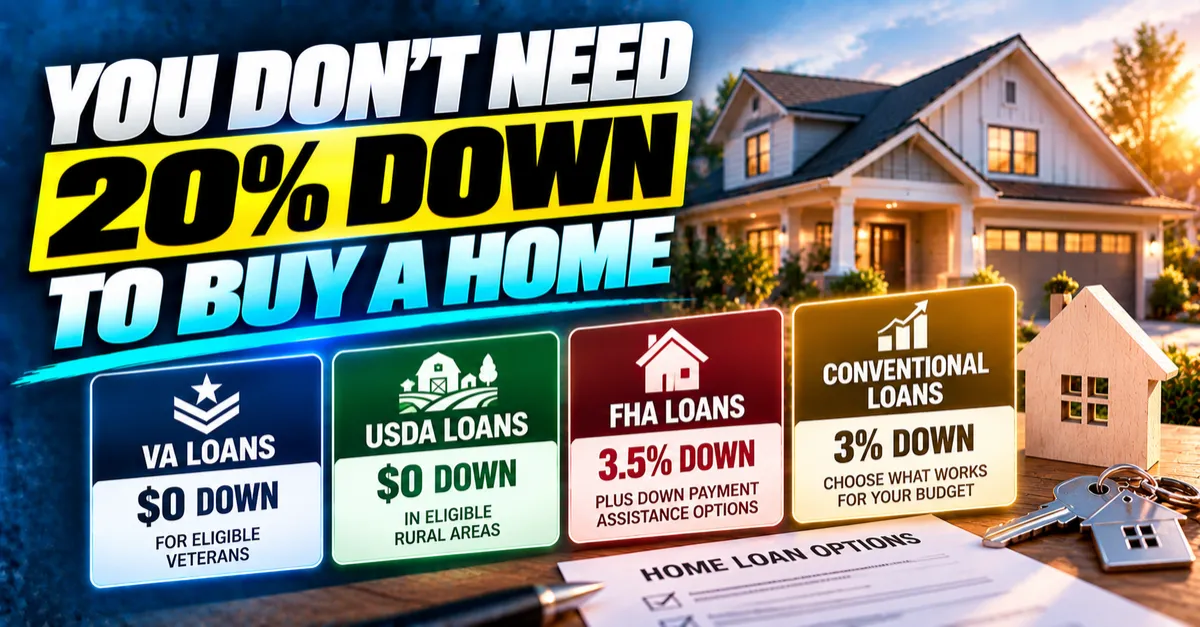
You Do Not Need 20 Percent Down to Buy a Home and Here Are the Four Loan Options That Prove It
The Myth That Is Keeping More First-Time Buyers on the Sidelines Than Any Other
Geoff Ricker at Bay Capital Mortgage hears it consistently from first-time homebuyers. You need twenty percent down before you can even start the process. It is one of the most persistent misconceptions in the mortgage world and it is keeping qualified buyers waiting for a target they never actually needed to hit.
The reality is that most buyers fall into one of four loan categories and every single one of them has a low or zero down payment option.
The Four Loan Categories and What Each One Offers
VA loans are available to eligible veterans and active duty service members and in most cases allow the purchase of a home with no down payment at all. The VA home loan benefit is one of the most powerful financial tools available to anyone who has served and using it to buy a home without a down payment is exactly what it was designed for.
USDA rural development loans offer another zero down path for buyers purchasing in eligible rural and suburban designated areas. Geographic and income eligibility requirements apply but for buyers in qualifying locations this program removes the down payment barrier entirely.
FHA loans are the most widely used option for first-time buyers and require as little as three and a half percent down. When paired with down payment assistance programs that exist at the state, county, and local level FHA financing can get a buyer into a home with very little out of pocket and in some cases nothing at all depending on the assistance available in their area.
Conventional financing starts at three percent down for qualifying first-time buyers and offers flexibility in how much more to put down based on what produces the most comfortable monthly payment for each buyer's specific situation. The down payment is not fixed at any particular number beyond the minimum and the right amount depends on the individual financial picture.
Why This Conversation Needs to Happen Before the House Search
Geoff's point is direct and worth internalizing. The right loan officer walks you through all of these options before you ever fall in love with a house. Not after. Not at the pre-approval stage when you have already identified the property you want. Before the search begins so the budget is real, the options are understood, and the process is navigated with clarity rather than discovered along the way.
Falling in love with a home before understanding the financing options produces unnecessary stress and sometimes missed opportunities. Starting with the financing conversation produces buyers who are confident, prepared, and positioned to move decisively when the right property appears.
Comment below and Geoff Ricker will reach out personally to walk through which option fits your specific situation best. Call 443-532-1620 or follow along at Bay Capital Mortgage for more real talk on home financing.
Sources
VA.gov
USDA.gov
HUD.gov
ConsumerFinancialProtectionBureau.gov
FannieMae.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|